The Absence of VAT in the United States: A Comparative Analysis of Taxation Models
What Is VAT and Why Is It So Popular?
Value-Added Tax is a consumption tax applied at every stage of the supply chain — from the manufacturer to the wholesaler, to the retailer, and finally to the end consumer. Each business in the chain charges VAT on its sales and can reclaim the VAT it paid on its purchases. The end result? Only the final consumer truly bears the tax burden, while businesses act as collection agents for the government.
VAT goes by different names around the world. In Australia, New Zealand, Canada, India, and Singapore, it's called Goods and Services Tax (GST). Despite the name difference, the mechanism is essentially the same — a multi-stage consumption tax with input credits.
The Absence of VAT in the U.S. Tax Landscape
The United States, despite being one of the world's largest and most developed economies, remains an outlier when it comes to its tax system. Unlike most industrialized nations, which have adopted a Value-Added Tax (VAT) as a primary revenue source, the U.S. relies on a decentralized sales tax system managed at the state and local levels. This unique approach raises questions about the feasibility and implications of introducing a VAT in the U.S., particularly in light of the potential benefits and challenges such a shift would entail.

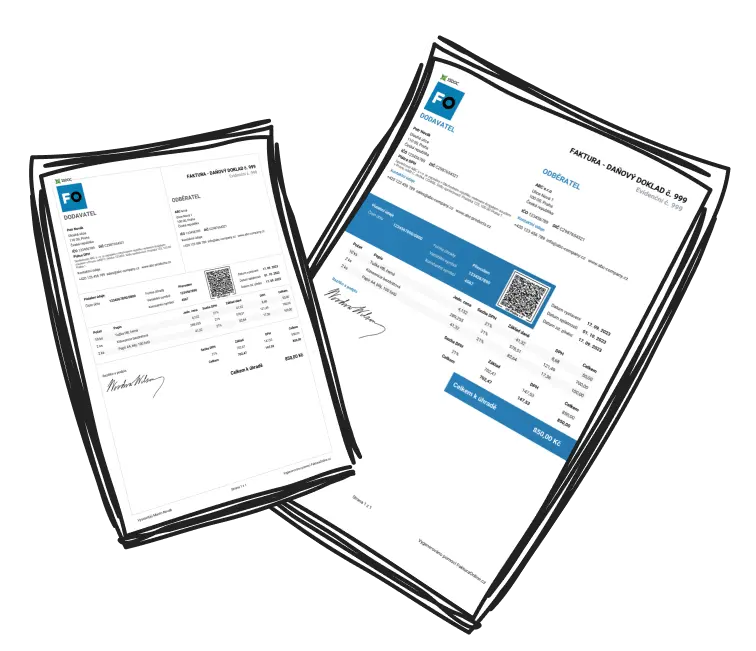
Unlike sales tax, which is levied only at the final point of sale, VAT is charged at every stage of the supply chain. This means that each business adds VAT on the value it contributes — allowing for more comprehensive tax collection across the entire economy.
Understanding VAT: A Global Perspective
Globally, VAT has been widely adopted due to its efficiency in generating revenue and its ability to capture a broader base of economic activity. In the European Union, for instance, VAT rates vary, with countries like Hungary imposing a standard rate of 27%, while Luxembourg applies a lower rate of 17%. The adaptability of VAT across different economic structures underscores its flexibility and effectiveness as a taxation tool.
Why Doesn't the U.S. Have VAT?
The reasons are a mix of history, politics, and structural complexity.
Federalism and State Power - The U.S. Constitution grants significant taxing authority to individual states. Sales taxes developed at the state level in the 1930s as a key revenue source, and states guard that power fiercely. A federal VAT would require major structural tax reform - and convincing 50 states to give up their independent tax systems is no small feat.
The Complexity of Transition - With over 13,000 taxing jurisdictions, each with its own rates, exemptions, and definitions of what's taxable, harmonizing the U.S. into a single VAT system would be an enormous undertaking. There were almost 13,000 rate changes across the U.S. in 2023 alone, illustrating just how dynamic and fragmented the system is.
Burden on Businesses - VAT requires businesses to collect and remit tax at every stage of the supply chain, keep detailed records, file regular returns, and comply with invoicing requirements. For American businesses accustomed to the sales tax model - where only final retail transactions are taxed - this would mean a significant increase in administrative costs.
Political Resistance - No politician wants to be the one who introduced a brand new tax on everyday purchases. VAT proposals surface from time to time in policy debates, but they consistently lack the political support needed to move forward.
What Would VAT Actually Mean for U.S. Businesses and Consumers?
Switching to VAT wouldn't just be a policy change on paper - it would reshape how millions of businesses operate day to day. Under the current sales tax system, most companies only worry about tax at the point of final sale. With VAT, every transaction in the supply chain becomes a taxable event. That means new invoicing requirements, regular VAT filings, and a system of input credits that needs careful tracking.
For small businesses especially, this added complexity could mean higher accounting costs and more time spent on compliance rather than growing the business. On the consumer side, the concern is straightforward: prices would likely go up. VAT rates around the world tend to be significantly higher than typical U.S. sales tax rates - often 15–25% compared to the 6–10% Americans are used to seeing at checkout.
Political and Economic Feasibility
The political feasibility of introducing VAT in the U.S. is another significant barrier. The decentralized nature of the U.S. tax system, combined with the strong tradition of state sovereignty over taxation, means that any attempt to implement a national VAT would likely face resistance from both state governments and the public.
The complexity of the current sales tax system, with its varied rates and exemptions, would make the transition to VAT a politically and logistically challenging endeavor. Coordinating across thousands of jurisdictions would require unprecedented cooperation between federal, state, and local governments.
Conclusion:
While the introduction of VAT in the United States could offer benefits such as a broader tax base and more consistent revenue streams, the challenges associated with its implementation are considerable. The federalist structure of the U.S. government, the complexity of the existing sales tax system, and the potential economic and political fallout make it unlikely that VAT will be adopted in the near future.